Coverage explained
Garage liability
Garage or auto-dealer liability addresses injuries and damage you cause through covered automotive operations. It is different from paying to repair a customer’s car in your possession or your own sale inventory.
Coverage
Start with what could be damaged, who could be injured or how money could be lost. These explanations show the coverage distinctions, realistic examples and policy details you can check yourself.
Liability from covered driving → garage or commercial auto.
Read the explanationInventory, customer cars and liability when vehicles move.
Coverage explained
Garage or auto-dealer liability addresses injuries and damage you cause through covered automotive operations. It is different from paying to repair a customer’s car in your possession or your own sale inventory.
Coverage explained
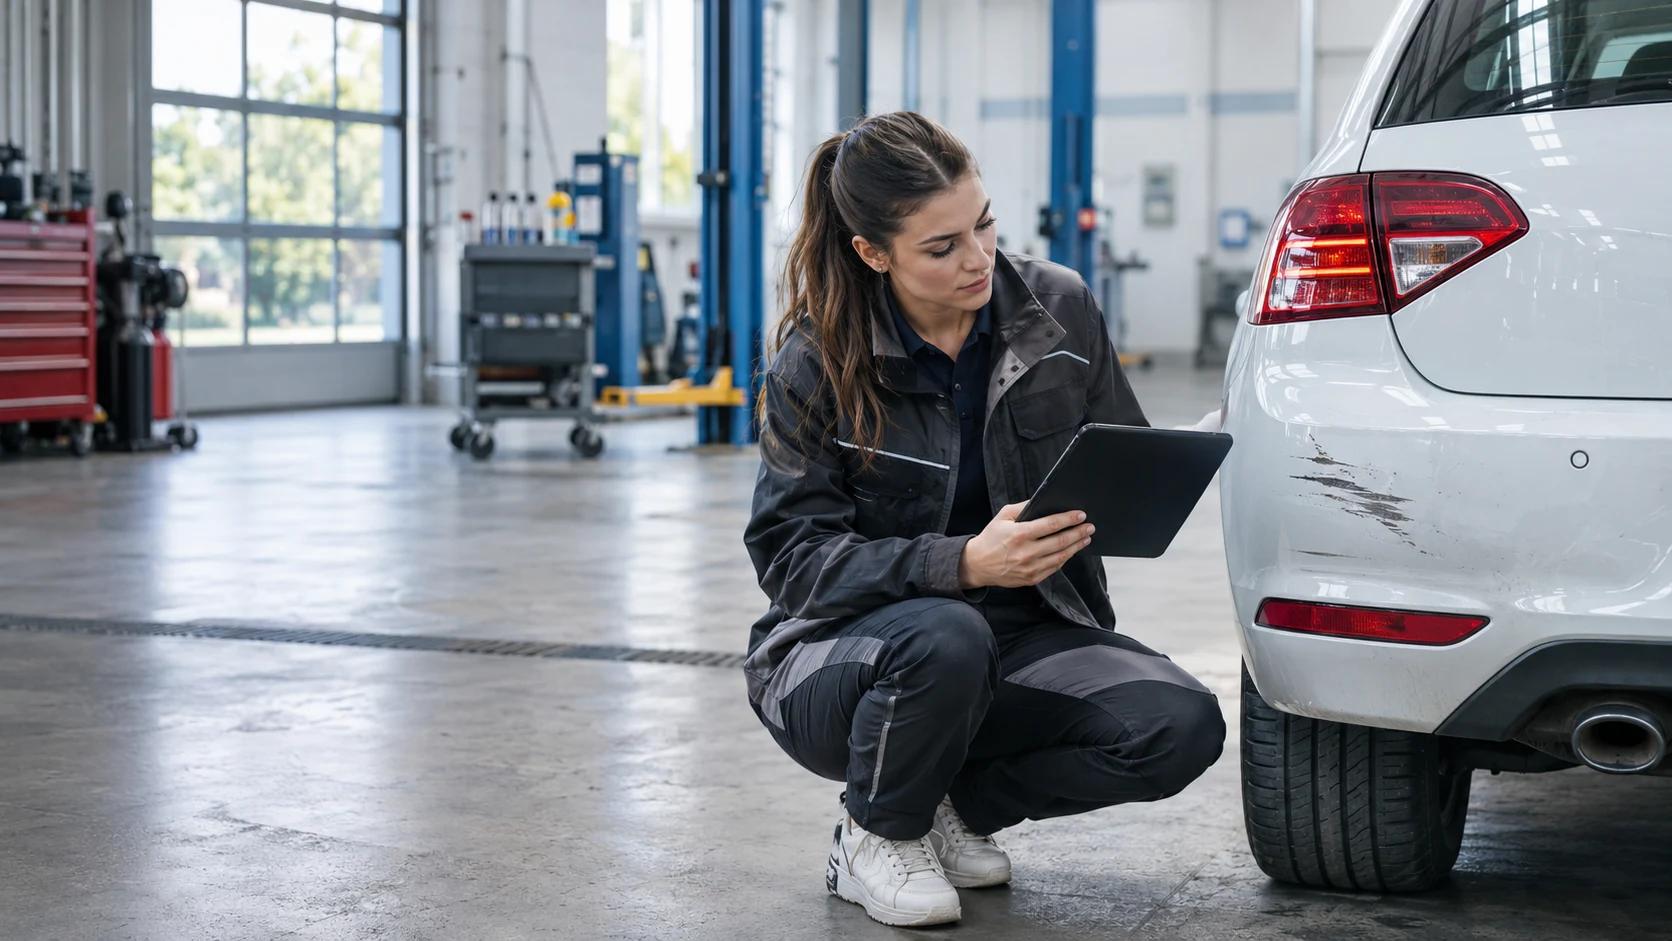
Garagekeepers addresses eligible damage to customer vehicles held for service, storage or parking. Compare the coverage basis, covered causes, deductibles and the highest combined value of cars you hold at once.
Coverage explained
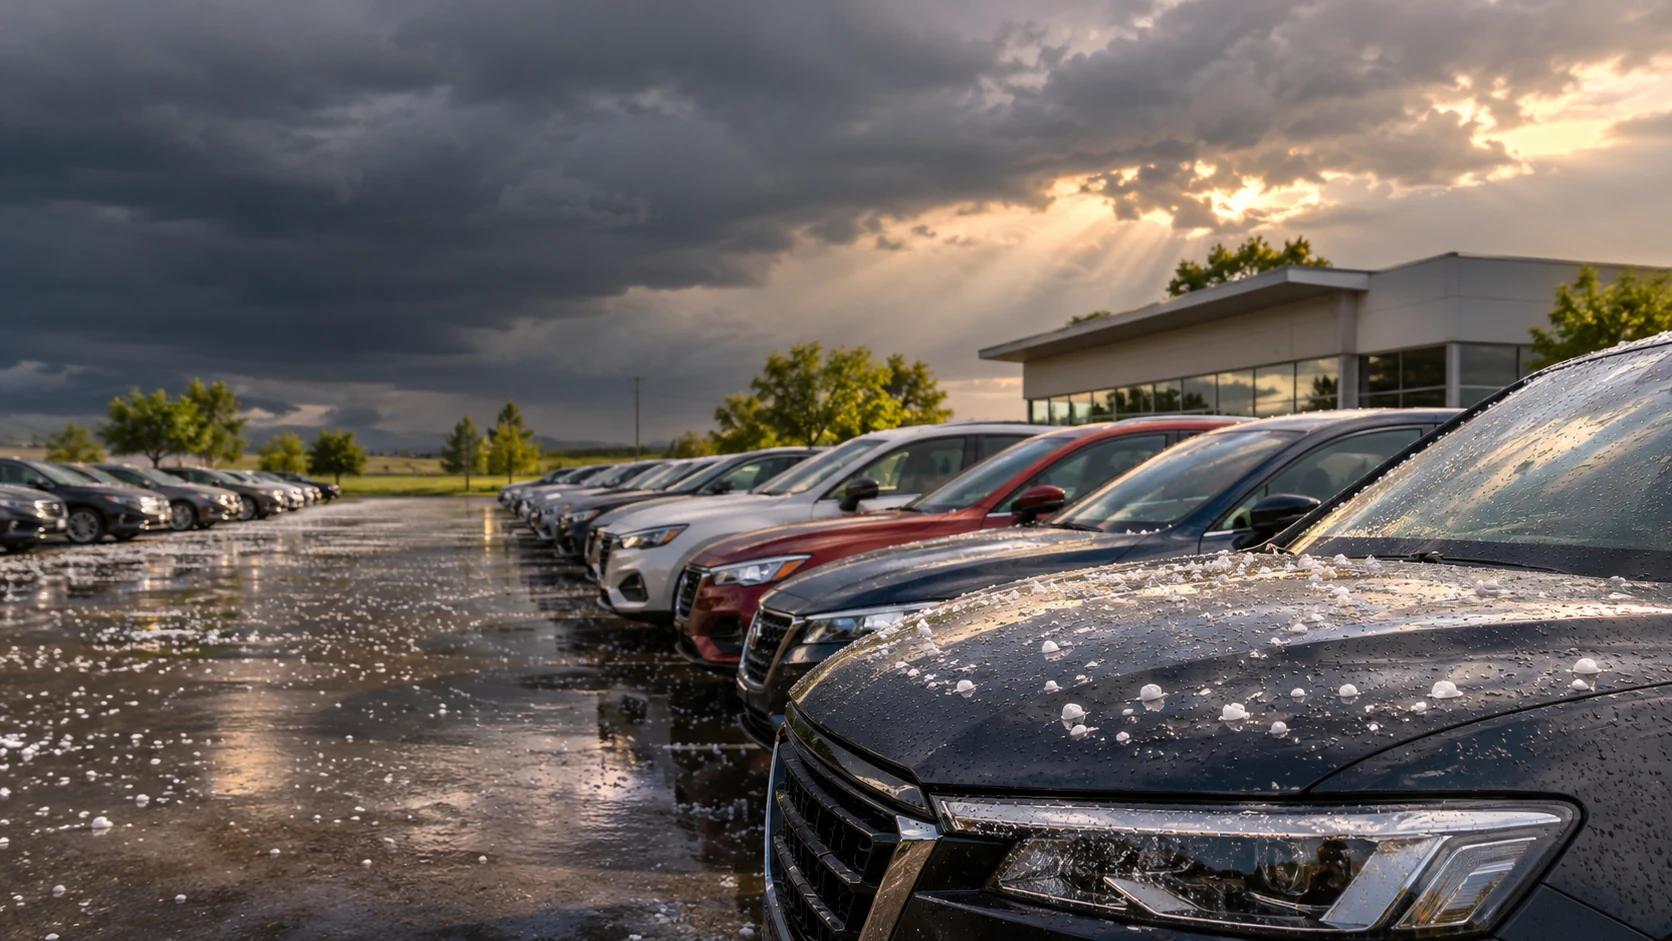
Dealers open lot is physical damage coverage for eligible sale inventory. The important numbers are your peak inventory value, any per-vehicle limit and the deductible that applies when one event damages many cars.
Coverage explained
Commercial auto addresses covered vehicle use by your business. Separate liability to others from damage to the vehicle itself, and distinguish owned vehicles from rentals and employees’ personal cars.
Buildings, income, visitor injuries and your workforce.
Coverage explained
General liability addresses claims that your premises or work injured someone or damaged their property. For automotive businesses, separate these claims from driving accidents and damage to cars left in your care.
Coverage explained
Property insurance addresses covered damage to your building and business contents. Business income and extra expense address qualifying interruption after a covered event. Insuring the building alone does not replace lost earnings.
Coverage explained
Workers’ compensation provides statutory benefits for covered work-related injuries or illness. Your states, employees’ actual duties and payroll determine how the policy should be set up—not just the job titles in your payroll system.
Coverage explained
Employment practices liability insurance addresses specified claims such as discrimination, harassment and wrongful termination. It can include defense costs even when an allegation is disputed, subject to the policy’s terms.
Transaction errors, digital events, theft and extra liability limits.
Coverage explained
Dealers errors and omissions addresses certain negligent mistakes in vehicle transactions. Look for the specific activities named in the coverage: title work, disclosures, odometer statements or finance and lease paperwork.
Cyber insurance for automotive businesses
Customer records. Card payments. The software that keeps work moving. Explore cyber cover for your dealership, repair shop or parking operation as part of your insurance program.
Coverage explained
Commercial crime insurance addresses specific theft and fraud losses. Employee theft, forged checks and a transfer you authorize after a fake email are different events; the coverage must match how the money was lost.
Coverage explained
Umbrella and excess coverage can add limits above specified underlying liability policies. The first task is checking which policies sit underneath it. A larger limit does not automatically fix an excluded claim.
Coverage depends on the issued policy, endorsements, limits, deductibles and facts of the loss. Examples are illustrative. Submitting an application does not start or change coverage.