Growing your inventory
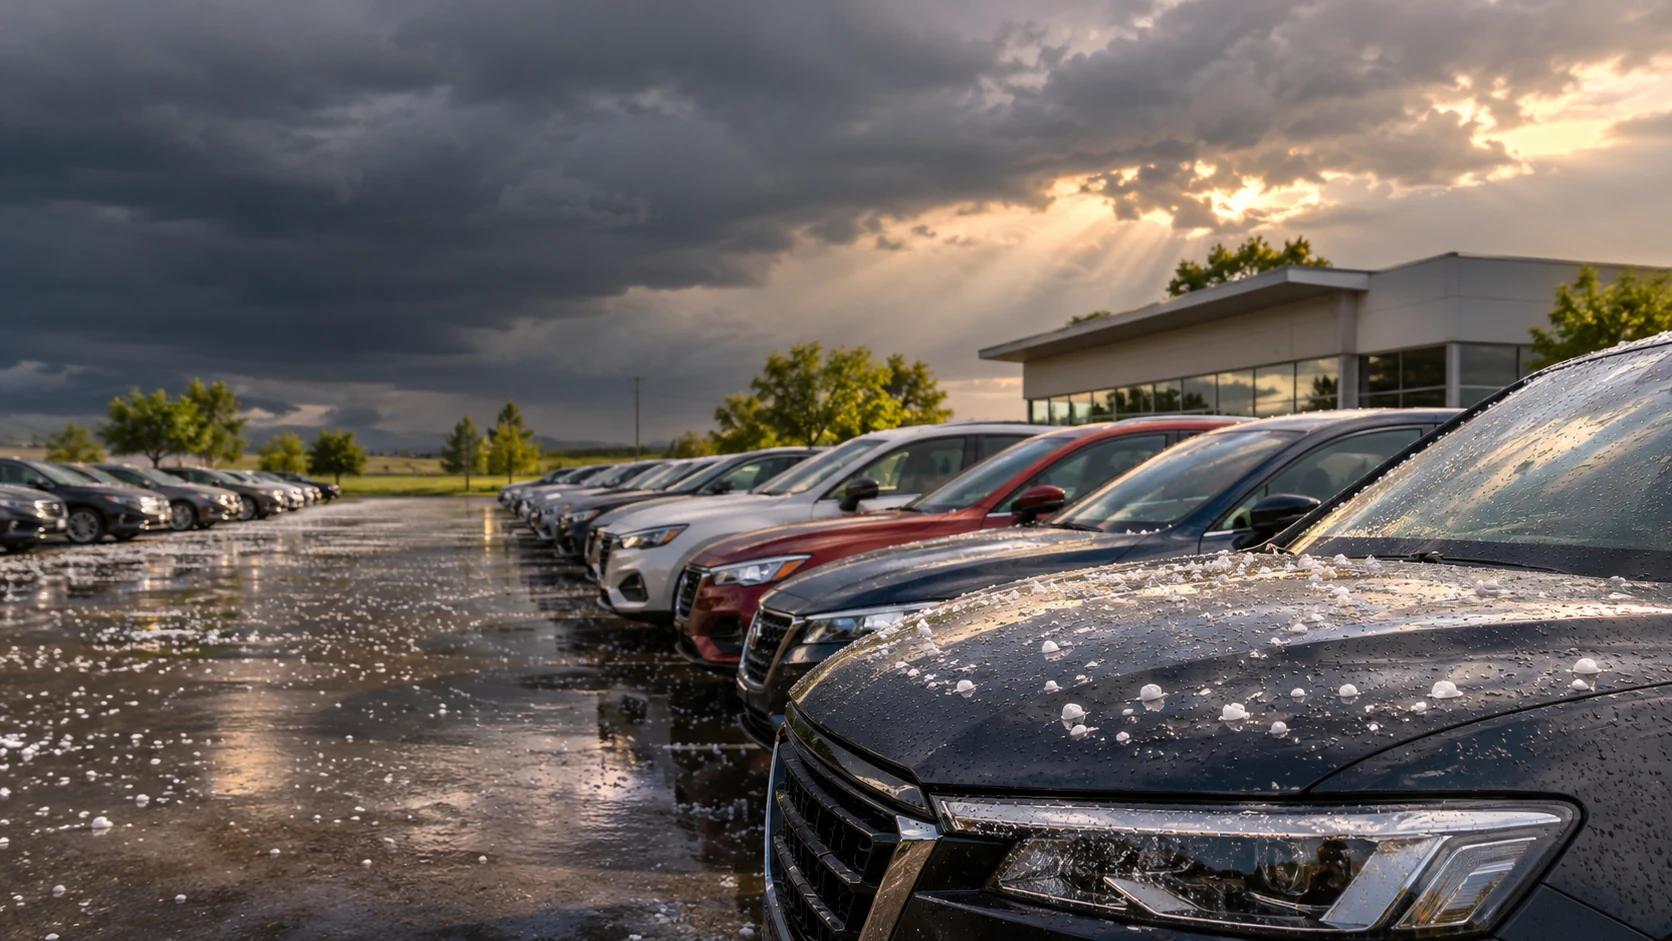
More stock means more value exposed to one event.
When you add cars, expand into higher-value vehicles or use an overflow lot, compare the largest value exposed at one time with your insurance—not just the number of spaces on the lot.
The starting point
Measure peak value at each location.
What to compare
Review reporting, transit and catastrophe terms.
Before you rely on it
Confirm limits for the larger inventory.
What changes in the insurance
| Change | Coverage to check | The detail that matters |
|---|---|---|
| More cars on the same lot | Dealers open lot | Total value that one storm, fire or theft event could affect. |
| Higher-value models | Per-vehicle limits and valuation | The most expensive car can exceed a cap even when the overall limit looks adequate. |
| Overflow or auction storage | Locations and transit | Addresses, temporary-storage rules and who transports the cars. |
| Larger floorplan borrowing | Lender interests and requirements | Loss payees, limits and required causes of loss. |
Work through it in this order
- 1
Calculate the peak
Use inventory records to estimate the largest total value expected, by location. Include seasonal peaks and cars in transit where applicable.
- 2
Model one shared event
Read per-car and per-event deductibles together. Calculate the amount you would retain if several vehicles were damaged.
- 3
Update the schedule or reporting
Follow the policy’s value-reporting and change process. Keep the acknowledged report and any revised limit confirmation.
The car count stays the same, but values double
Forty cars valued at $15,000 each represent $600,000. Forty at $30,000 each represent $1.2 million. The number of spaces did not change; the exposed value did. This is an inventory illustration, not a suggested insurance limit.
Your preparation checklist
Common questions
Can I use my floorplan balance as the insurance value?
Not without comparing it with the policy’s valuation basis and all eligible inventory. Loan balances and insured values can differ.
Does adding an overflow lot require notice?
Check the policy’s location and temporary-storage terms. Do not assume a nearby address is included because the main lot is insured.
Coverage depends on the issued policy, endorsements, limits, deductibles and facts of the loss. Examples are illustrative. Submitting an application does not start or change coverage.
Further reading
Oregon DAS: garage and garagekeepers coverage ↗NAIC: small business insurance ↗Your next step
Describe the change. Keep the details together.
Start an application with the change date, affected operations and available documents. The insurer must confirm any requested coverage change.