Workers’ compensation
Help for employees hurt while doing their jobs.
Workers’ compensation provides statutory benefits for covered work-related injuries or illness. Your states, employees’ actual duties and payroll determine how the policy should be set up—not just the job titles in your payroll system.
What it protects
Covered employee work injuries and illness.
The key distinction
Different from customer-injury liability.
Start your review
Check duties, payroll and work states.
What it can pay for
Benefits and employer obligations vary by state. Review the rules for each state where employees work.
Treatment and wage benefits
Covered medical treatment and applicable wage-replacement, disability or other statutory benefits for a work-related injury or illness.
Employers liability
A separate policy part can address certain employer-liability claims arising from work injuries. It has its own limits and exclusions.
What belongs elsewhere
Customer injuries
Workers’ compensation is for the covered workforce. A visitor’s injury belongs under the appropriate liability coverage.
Read the explanationDiscrimination or termination claims
An employment dispute is not the same as a work injury. Employment practices coverage addresses specified allegations.
Read the explanationA technician injures a shoulder
Illustrative example — the policy terms and facts determine the outcome.
- 1
The injury
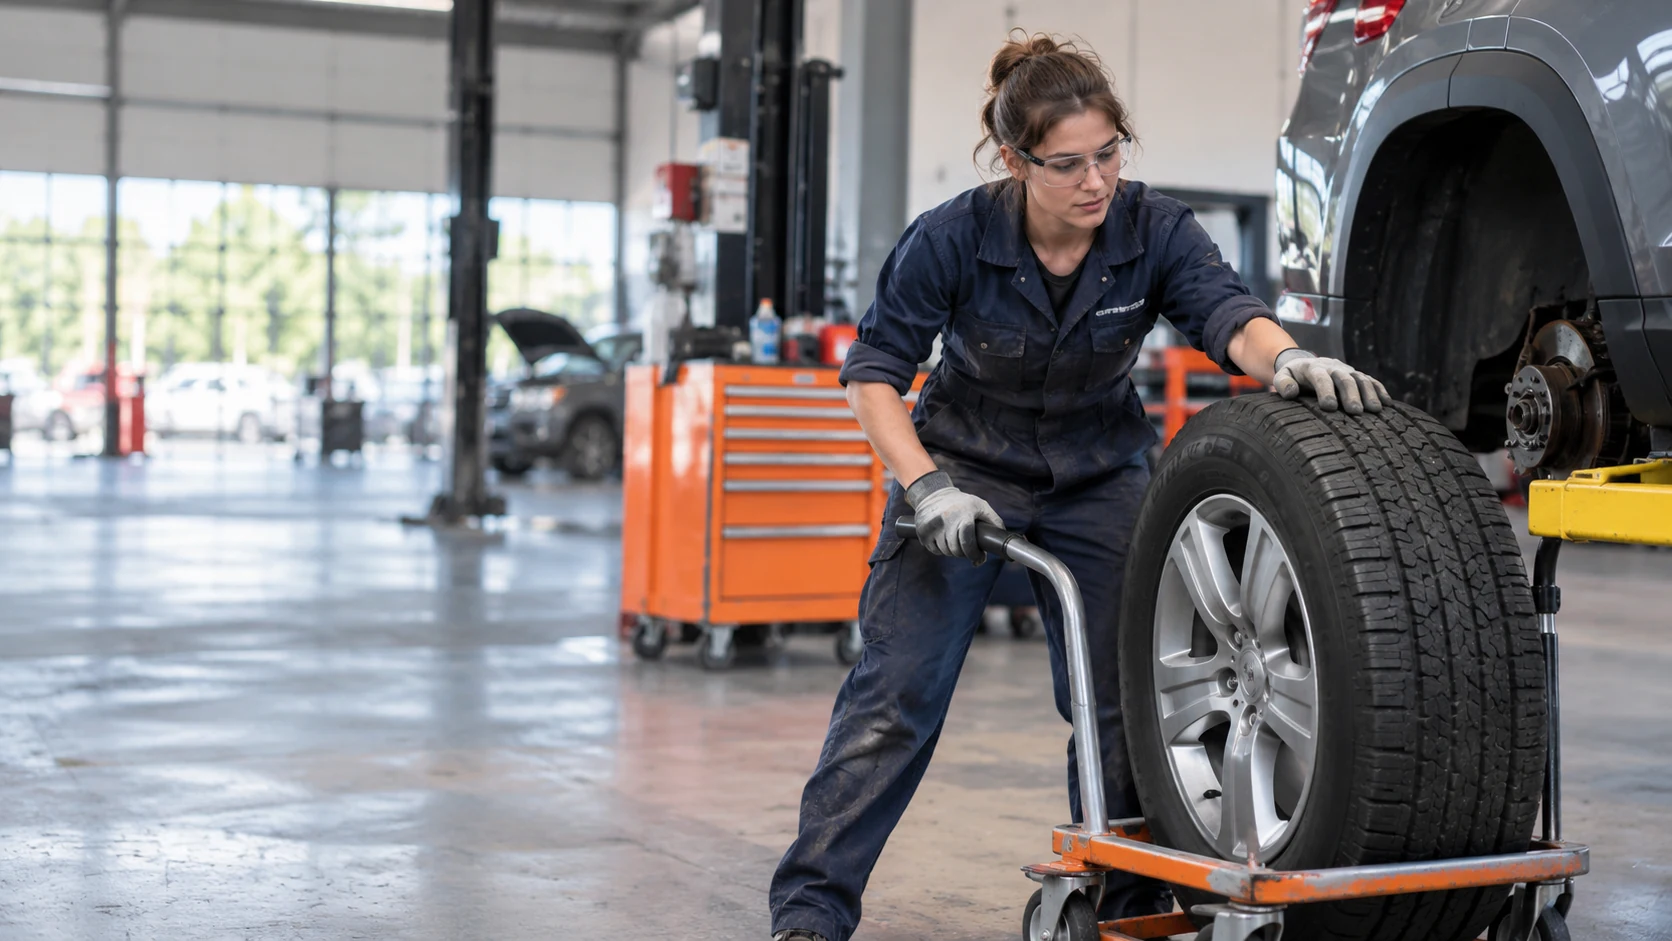
A technician strains a shoulder while handling a wheel during a shift.
- 2
The response
Use the employer’s injury-reporting process and the state’s treatment rules. The workers’ compensation insurer determines benefits under the applicable law.
- 3
The records
Keep the date, work activity, reported injury and payroll/classification records. Prompt reporting supports the claim process.
Read these parts of your policy
| Find this | What to check | Why it matters |
|---|---|---|
| States | Listed states and any other-states provisions; places staff actually work. | Adding operations across a state line can require a change. |
| Classifications | Technicians, sales, office staff, drivers and attendants by actual duties. | Different work carries different classifications and rates. |
| Payroll and audit | Estimated payroll, records needed and the premium-audit process. | Final audited payroll can change the premium. |
| People included | Owners, officers, temporary staff and subcontractors; applicable elections. | An exemption or independent-contractor label is not the same as automatic exclusion. |
Your practical checklist
Use these boxes as you gather the details. They stay on this page; nothing is submitted.
Common questions
Is it required if I have only one employee?
Requirements depend on the state, business and worker status. Check the relevant state workers’ compensation authority; do not assume small headcount creates an exemption.
Does calling someone a contractor settle the issue?
No. Worker status depends on applicable law and the actual relationship. Keep contracts and insurance records, and accurately describe the work.
Why can the premium change after the year ends?
Policies commonly start with estimated payroll. An audit compares actual payroll and classifications with those estimates and can produce an adjustment.
Coverage depends on the issued policy, endorsements, limits, deductibles and facts of the loss. Examples are illustrative. Submitting an application does not start or change coverage.
Further reading
Triple-I: workers compensation insurance ↗NAIC: small business insurance ↗Your next step
Put your coverage comparison to work.
Start with your business details and the coverage you want to review. Add current policies and schedules if you have them.