Possibly—but a repair shop’s overall equipment limit does not by itself establish coverage for technicians’ personally owned tools. At renewal, locate the policy provision or endorsement that includes employee-owned property and confirm its limits, valuation, covered losses and locations. Prepare separate values for shop-owned equipment and technicians’ tools before comparing the expiring policy with proposed terms.
Separate ownership before comparing coverage
Chubb’s business-contents guidance describes company property, including equipment and machinery. That description does not confirm that a technician’s personally owned toolbox qualifies under a shop’s policy. Resolve ownership in the actual covered-property wording.
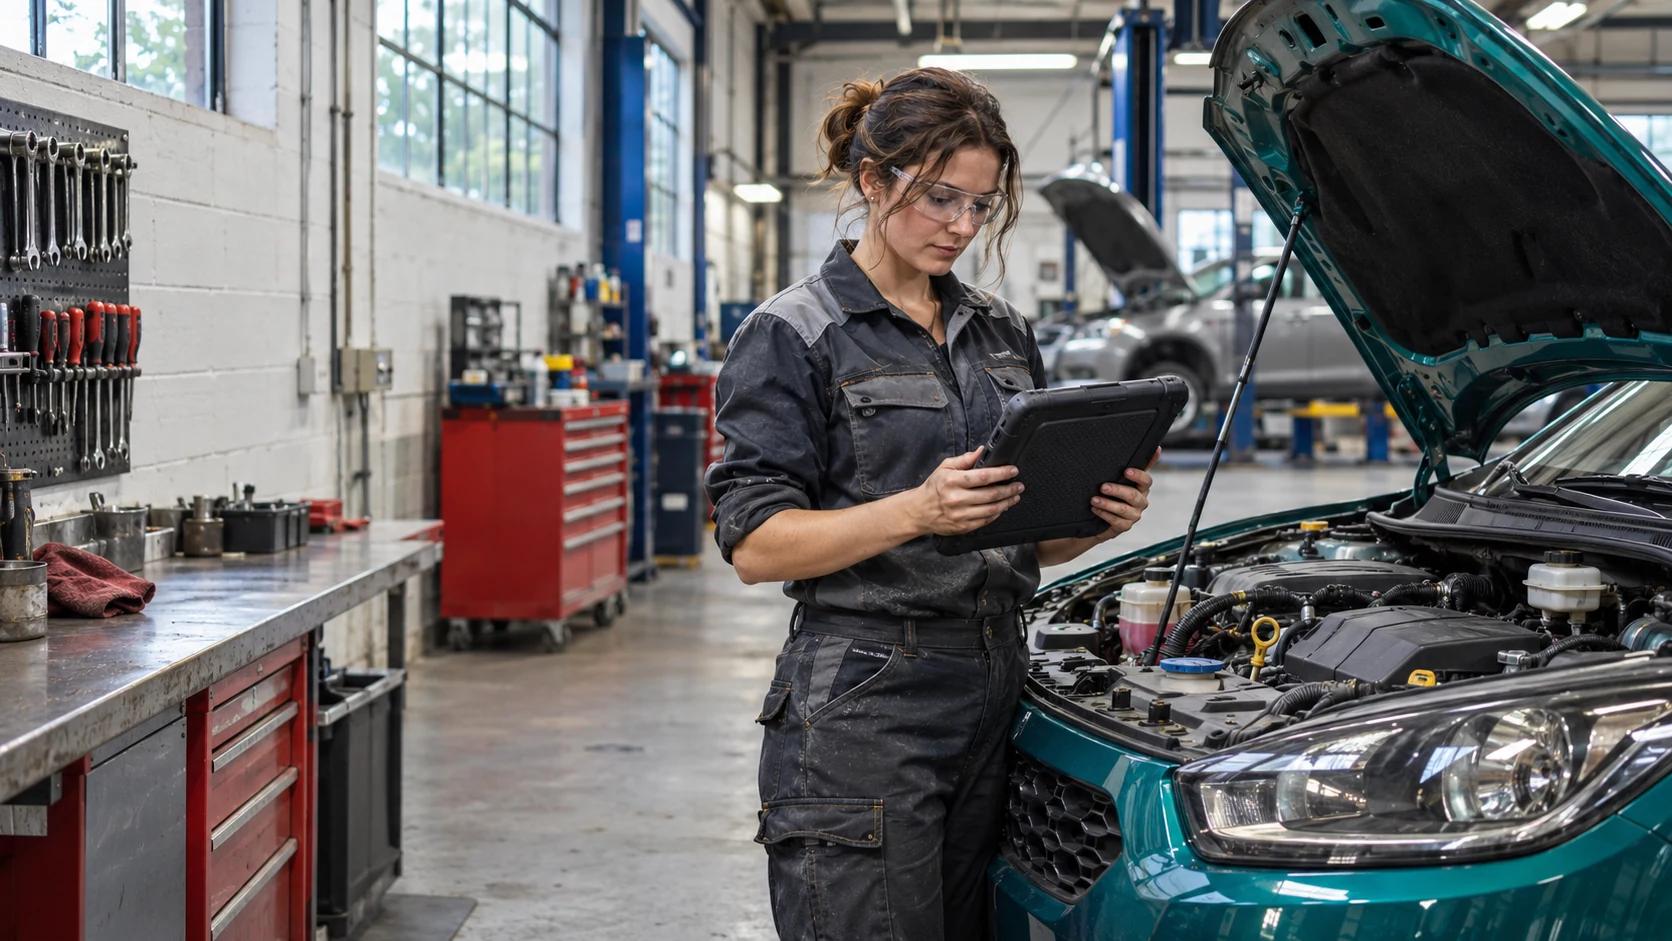
Build three labeled lists: shop-owned assets, rented or leased equipment, and employee-owned tools. A shop-owned lift and a technician’s personal hand tools should not disappear into one unlabeled equipment total. Record the owner, item description and usual storage location for each.
Keep customer vehicles separate from these tool values. Travelers discusses customer-auto custody under garagekeepers, separately from property protection for the shop’s tools and equipment.
Sources: Chubb: How Much Insurance Do You Need to Protect Your Business Contents? · Travelers: Insurance for Auto Repair Shop Mechanics
Find the provision that includes employee tools
Travelers’ auto-repair page identifies employee tools and equipment coverage within its Garage Amendatory Provisions endorsement. This is an example of the named Travelers product—not a feature to assume in every commercial property policy.
Ask the broker to identify the applicable provision, rather than relying on a quote heading that says tools or contents. These are comparison questions, not a universal carrier checklist:
- Which employee-owned items qualify: hand tools, diagnostic devices, cabinets or other equipment?
- Are those items included in the covered-property definition or through an endorsement?
- Does the proposed renewal retain that provision and the same item eligibility?
- How does the policy handle loss payment for property owned by an employee?
Sources: Travelers: Insurance for Auto Repair Shop Mechanics
Read the employee-tools limit separately
New York’s Department of Financial Services lists employees’ personal property among potential property coverage options and notes that insurers may offer variations. Locate the limit that applies to those tools and compare it with their values—not simply the largest property number on the declarations.
Hypothetical example: A shop adds two technicians, each bringing a toolbox and a diagnostic device. Its shop-owned equipment value barely changes. For renewal, update the employee-owned total and ask which limit would apply if all technicians’ tools were damaged in one fire. This is a coverage question, not a prediction that the event or items would be insured.
- Is there a combined employee-tools limit, a per-employee limit, a per-item limit or more than one?
- Is that protection part of the main property limit or additional to it?
- What deductible applies, and how would it apply when several employees’ tools are damaged in one event?
- Does the renewal change any of these terms even if the overall equipment limit stays the same?
Sources: New York Department of Financial Services: Information for Small Businesses · Travelers: Insurance for Auto Repair Shop Mechanics
Check covered losses and how tools would be valued
Being included as covered property is only one step. New York’s Department of Financial Services explains that property forms differ in the causes of loss they cover and the exclusions they apply. A theft question therefore needs more than confirmation that tools appear in a property schedule.
That guide distinguishes actual cash value, which deducts depreciation, from replacement cost, which does not. Check the employee-tool valuation specifically rather than assuming it matches the shop-owned equipment.
Tool damage and interrupted work are separate questions. Sentry says its business personal property plan does not cover income lost because damaged equipment cannot be used. If unavailable employee tools stop repairs, ask separately whether that event satisfies the business income wording.
- Does the employee-tools provision use the same covered causes of loss as the main property coverage?
- Are there relevant storage, security or theft conditions? How are unexplained missing items treated?
- What conditions must be met to receive replacement-cost payment?
Sources: New York Department of Financial Services: Information for Small Businesses · Sentry: Business Personal Property Insurance Coverage
Map tools that leave the shop
Sentry describes off-premises and transit protection for its business personal property product. Do not transfer that description to another policy or assume it includes property owned by employees.
Prepare a short movement list: tools that remain at a work bay, items technicians take home, and equipment moved between repair locations or placed in temporary storage. Ask the broker to check each situation against the employee-owned property provision.
Separate the tools from the vehicle carrying them. This review addresses the tools; it does not establish coverage to repair a business or employee vehicle.
- Which insured locations and geographical territory apply?
- Does employee-tools protection continue in transit or at temporary locations?
- Are limits, deductibles or security conditions different away from the shop?
Sources: Sentry: Business Personal Property Insurance Coverage
Prepare a renewal file and resolve unanswered questions
Chubb’s contents guidance emphasizes documenting equipment values. For this review, assemble an ownership-labeled inventory, dated photos, available receipts, item identifiers and estimated current replacement values. Keep a backup away from the shop.
Record both the combined employee-owned value and the largest individual technician’s tool set. Identify shared or loaned tools so the same asset is not counted twice. These totals let you ask about both a single technician’s loss and an event affecting several work bays.
Compare the expiring and proposed provisions side by side. Keep unresolved ownership, location, valuation and limit questions visible rather than substituting a larger equipment total for an answer.
For an Atlas Automotive quote request, organize these values and describe planned hires or changes in tool storage and movement. Availability varies by carrier, state and risk. This is general education and does not bind or establish coverage; policy wording controls.
Sources: Chubb: How Much Insurance Do You Need to Protect Your Business Contents? · New York Department of Financial Services: Information for Small Businesses
Your preparation checklist
- Separate shop-owned, rented or leased, and employee-owned equipment.
- Update combined employee-tool values and the largest individual tool set.
- Collect available descriptions, identifiers, photos and purchase records.
- List usual storage locations and any movement away from the shop.
- Identify the provision that includes employee-owned tools.
- Compare applicable limits, deductibles, covered losses and valuation.
- Check business income separately if unavailable tools could interrupt repairs.
- Resolve unanswered questions before relying on the renewal.
Sources and editorial approach
Atlas publishes practical insurance education using public regulatory and insurer materials. Insurer examples describe their own products and do not establish Atlas market access. Your policy and endorsements determine actual coverage. This article is general information; it does not bind coverage or replace advice about your particular business.
- Travelers: Insurance for Auto Repair Shop Mechanics
Opened HTML. Identifies employee tools and equipment within Travelers’ Garage Amendatory Provisions endorsement and separates shop property from customer-vehicle custody. Product-specific; no Atlas appointment or availability is established.
- Sentry: Business Personal Property Insurance Coverage
Opened HTML. Describes Sentry’s off-premises and transit protection and distinguishes direct physical loss from lost income. Does not confirm employee ownership eligibility or another policy’s terms.
- Chubb: How Much Insurance Do You Need to Protect Your Business Contents?
Opened HTML. Describes company contents and documenting equipment values. Does not establish that employee-owned tools qualify under a repair shop’s policy or that Atlas has access to a Chubb product.
- New York Department of Financial Services: Information for Small Businesses
Opened HTML. New York small-business education lists employee personal property as a possible coverage option and explains property forms, valuation and periodic review. Not used as a legal requirement.
Have a correction or a question? Contact Atlas.